Why being mortgage-free sounds so good right now
When you’ve got a fixed-rate mortgage and a little extra cash each month, the payment can start to feel less like a “good debt” and more like a weight you keep choosing to carry. Rates and prices have made everything else feel less predictable, so a guaranteed win—owing less—sounds unusually appealing. It’s simple. It’s concrete. And it doesn’t depend on markets cooperating.
But “mortgage-free” bundles together different benefits that don’t all matter equally. Some of the payoff is math (interest you never send to the bank). Some is day-to-day flexibility (the month your payment disappears). Some is risk and mental load (fewer fixed bills when life gets messy). The hard part is deciding which of those you’re really buying with each extra dollar.
Before you send extra money, what’s your real starting line?
Each extra dollar can buy a different mix of “math,” “flexibility,” and “less worry,” but the mix depends on where you’re starting. Most people skip that check and just pick a round number to throw at principal. Then a surprise expense shows up—car repair, medical bill, job wobble—and the plan gets shaky because the cash is already locked inside the house.
Start with three quick facts. What’s your current mortgage rate, and is it fixed for the life of the loan? What other debt is costing you more (credit cards, personal loans, even a high-rate car note)? And how many months of true emergency cash do you have in an account you can reach in a day or two? If that cushion is thin, extra principal can feel “safe” while actually making you less able to handle a short-term hit.
Then define your target. Are you trying to cut total interest, lower your future monthly obligations, or reduce the chance you’ll feel trapped if income drops? Pick one as the main goal, because you’ll measure progress differently. With that starting line, you can compare extra payments against the alternatives without guessing.
Benefit #1 shows up on paper: interest you never pay
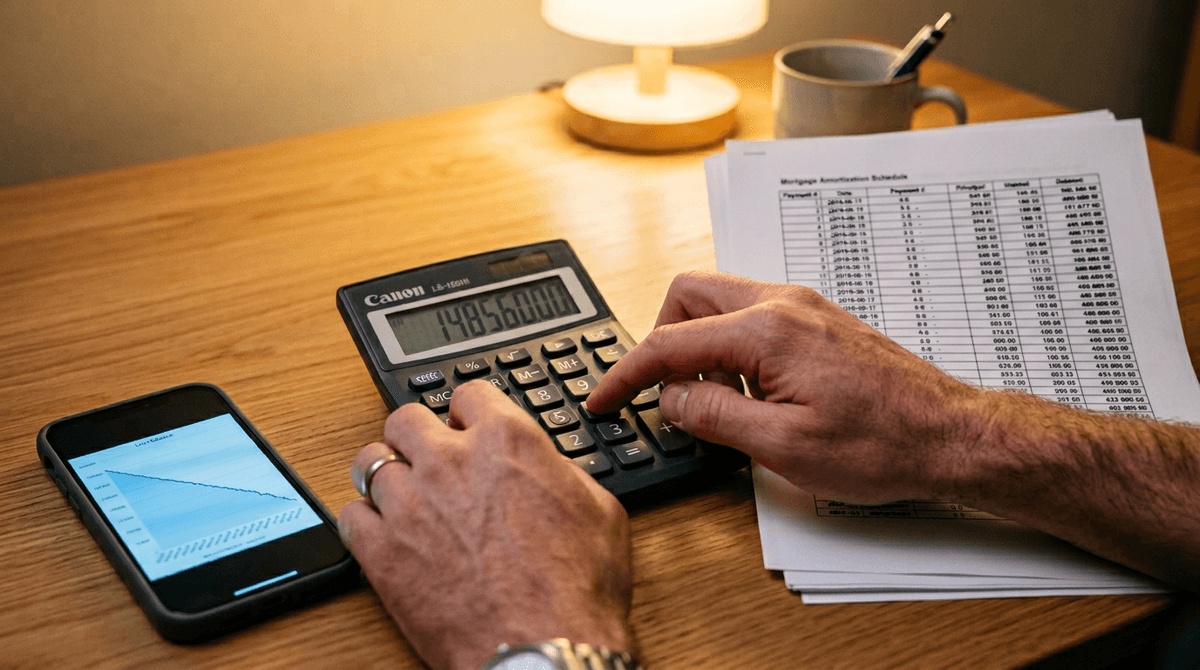
Once you know your rate, debts, and cash cushion, the cleanest benefit to measure is the interest you don’t pay. In plain terms: every extra dollar that hits principal stops future interest from being calculated on that dollar. If your fixed rate is 6%, an extra $1,000 is like earning a risk-free 6% “return” in saved interest—before taxes—and it lasts for the remaining life of the loan.
The catch is timing. Early in the mortgage, a larger share of each payment goes to interest, so extra principal usually saves more total dollars over time. Late in the loan, you still save interest, but there are fewer months left for the savings to stack up. That’s why a payoff calculator matters: it turns “I paid extra” into “I shaved X years and saved $Y.”
Lenders handle extra payments differently. If you don’t mark it as “principal only,” or if they advance your due date, your payoff timeline can drift. Before you automate anything, confirm how your servicer applies extra funds and how you’ll track the principal balance month to month.
Imagine the month the payment disappears—what would change?
That same payoff calculator can also answer the more personal question: what happens in the first month you don’t owe the payment anymore? Picture your current monthly principal-and-interest amount landing back in your checking account. If it’s $2,200, that’s $2,200 you can redirect—into retirement accounts, a college fund, rebuilding cash, or simply lowering the minimum income your household needs to function.
This is the “cash-flow” benefit, and it’s different from interest saved. It matters most if your budget runs tight, your income is uneven (commission, self-employment), or you’re thinking about a job change. If you can cover your life on one income once the mortgage is gone, you’ve changed your risk profile in a way the interest math doesn’t capture.
The limitation is that you don’t get that flexibility until the finish line. If paying extra leaves you with $1,000 in liquid cash and a $6,000 HVAC replacement hits, you may end up using a credit card and losing the advantage. That’s why it helps to put a date on it: “payment-free by June 2033” or “by age 55,” then check whether the path there still leaves you enough cash to handle real life.
When peace of mind is the main return
Putting a date on it makes the plan feel real, but the day-to-day payoff often shows up earlier as fewer “what if” spirals. You look at your fixed bills and see one less obligation looming over every budget decision. If you’ve lived through a layoff, a bad sales quarter, or a family health scare, shrinking the mortgage balance can feel like buying room to breathe, even before the payment disappears.
This is the risk benefit: a smaller required monthly nut, and less chance you’ll feel forced to sell or borrow at the wrong time. For example, if your household could stay current for months on savings because the mortgage is gone (or close to gone), you can handle an income dip without scrambling. That calm is hard to price, but it’s not imaginary.
The real-world cost is liquidity. Extra principal doesn’t help when the roof leaks next week, and a home equity line isn’t guaranteed or instant. If peace of mind is your main return, you still need cash outside the house to make that peace durable.
What you give up by turning cash into home equity
That liquidity problem is the headline cost of extra principal: you’re swapping dollars you can use on Tuesday for equity you can only reach by selling or borrowing. In a normal month, that may feel fine. In an abnormal month—job gap, insurance deductible, major repair—you can’t “unpay” the mortgage to cover the bill, and a HELOC can be slow, denied, or expensive right when you need it.
You also give up optionality. If you send $800 extra each month and later decide you’d rather max a 401(k), build a bigger cash buffer, or take a lower-stress job, the money you already locked into the house doesn’t pivot with you. And while “saved interest” is a real return, it’s capped at your mortgage rate; diversified investing could do better over long periods, but it can also do worse in the exact years you planned to rely on it.
There’s a smaller, practical downside too: faster payoff can concentrate your wealth in one asset. If home prices dip in your area, your net worth statement can swing more than you expected. The next decision is whether that concentration is acceptable for your timeline and sleep.
How aggressive should you be without regretting it later?
That concentration question is where “how aggressive” becomes practical. A common pattern is to pick an extra-payment number that feels heroic, then quietly resent it when the first expensive month hits. If you’re checking the account balance before every grocery run, you didn’t buy freedom—you bought a tighter leash.
Set a floor first: keep a cash buffer you can access in a day or two, then clear any debt that costs more than your mortgage rate. After that, choose a pace you can keep through boring months. One simple rule is “half the surplus”: if you have $800 left after bills and savings, send $400 to principal and direct $400 to investing or cash. If that still feels tight, start smaller and schedule an automatic step-up every 6 or 12 months.
One constraint to plan for: extra-payments are easy to start and hard to stop without feeling like you’re backsliding. Your next move is to pick a payoff date that doesn’t strain cash flow, then automate the smallest extra amount you’d feel comfortable paying even in a rough quarter.
A simple next-step checklist for this week
That “smallest extra amount you’d still pay in a rough quarter” is your anchor—now make it real with a few quick checks this week. Pull your latest statement and confirm your exact rate and remaining term, then verify with your servicer how to apply “principal only” and whether extra payments change the due date. Run a payoff calculator with two numbers: your anchor amount and a stretch amount, and write down the payoff date and interest saved for each.
Then pressure-test liquidity. List the next 12 months of likely large expenses (insurance deductibles, car tires, home repairs) and confirm you still keep your emergency cash in a same-day account after making extra payments. If you don’t, reduce the extra payment until you do—because a credit-card “bridge” can erase the win fast.
Finally, pick one priority for the next 90 days: interest saved, future cash flow, or lower stress. Set an automatic monthly principal payment at the anchor amount, and set a calendar reminder for 90 days from today to reassess your surplus and step it up only if the plan still feels easy.